
During a period when tax authorities are strengthening management of e-commerce activities, especially revenue generated on e-commerce platforms, the question "Is it a problem if I sell online without issuing invoices" is no longer a theoretical concern but has become a real legal risk for many business households.
This article clarifies the obligation to issue invoices for online sellers, the applicable legal basis, the timing of invoice issuance, and the legal consequences of non-compliance.
Is issuing invoices mandatory when selling online?
Business households and individual business operators with annual revenue exceeding 01 billion dong, or selling assets that require registration of ownership or usage rights, must use electronic invoices with tax authority codes or electronic invoices initiated from electronic cash registers connected to the tax authority's data system (Decree 254/2026/NĐ-CP, Article 6, Clause 1, Point d, effective from 01/07/2026; Decree 68/2026/NĐ-CP, Article 8, Clause 5, amended by Decree 141/2026/NĐ-CP). Some cases do not require electronic invoices, such as income from real estate rental, or acting as agents for lottery tickets, insurance, or multi-level sales where the enterprise has already withheld taxes (Decree 254/2026/NĐ-CP, Article 7).
Business households and individual business operators with annual revenue of 01 billion dong or less, meeting the conditions and having the need, may register to use electronic invoices (Decree 68/2026/NĐ-CP, Article 8, Clause 5, Point b, amended by Decree 141/2026/NĐ-CP). For the specific activity of selling goods and providing services directly to consumers (retail, except automobiles, motorcycles, motorbikes and other motor vehicles; eating and drinking; restaurants; hotels and other activities mentioned in the documents), Decree 254/2026/NĐ-CP, Article 6, Clause 1, Point c requires the use of electronic invoices from electronic cash registers. Decree 254/2026/NĐ-CP, Article 4, Clause 1, also stipulates that when selling goods or providing services, the seller must issue an electronic invoice to give to the buyer, except in cases not requiring electronic invoices as specified in Article 7 of that Decree. If your revenue during the tax year exceeds 01 billion dong, you must use electronic invoices with tax authority codes or electronic invoices initiated from electronic cash registers connected to the tax authority's data system, and must register within 30 days from the last day of the tax period with cumulative revenue exceeding 01 billion dong (Decree 68/2026/NĐ-CP, Article 8, Clause 5, Point c, amended by Decree 141/2026/NĐ-CP). Please ask your accountant whether your case requires using electronic invoices.
For business households selling goods on e-commerce platforms, the platform operator is responsible for providing buyer information, transaction-related information, delivery timing, and confirming order completion status on the system so that the seller can issue electronic invoices in accordance with regulations (Decree 254/2026/NĐ-CP, Article 19, Clause 2).
Read more: Must revenue from e-commerce platforms be declared for taxes?
Applicable legal basis for online sellers
The key document on electronic invoices that online sellers need to understand clearly is Decree 254/2026/NĐ-CP, effective from 01/07/2026 (Article 43, Clause 1). From that date, Decree 123/2020/NĐ-CP and Decree 70/2025/NĐ-CP cease to be effective (Decree 254/2026/NĐ-CP, Article 43, Clause 2, Points a and c).
Timing for issuing invoices when selling online
One of the common misconceptions is that invoices only need to be issued after receiving payment. This understanding is not legally correct.
According to current regulations, the timing of invoice issuance is the time of transfer of ownership or usage rights of goods, regardless of whether payment has been received (Decree 254/2026/NĐ-CP, Article 9, Clause 1, effective from 01/07/2026).
For online sales, this timing is usually understood as:
- The order has been successfully delivered to the customer
- Whether the payment is cash on delivery or paid in advance does not change the obligation to issue invoices
Delivery before invoicing or backdating invoice issuance may be considered improper invoicing timing under Decree 254/2026/NĐ-CP, Article 9.
Read more: Everything about electronic invoices: When to issue, how to handle errors
Is there a penalty for not issuing invoices when selling online?
What penalties apply for not issuing invoices when selling online?
According to Decree 125/2020/NĐ-CP, Article 24 Section 3, as amended by Decree 310/2025/NĐ-CP, Article 1 Section 14 Point b (effective from 16/01/2026), the act of not issuing invoices when selling goods or providing services as required is subject to fines based on the number of unissued invoices:
- from 1,000,000 VND to 2,000,000 VND for 01 invoice number;
- from 2,000,000 VND to 10,000,000 VND for 02 to under 10 invoice numbers;
- from 10,000,000 VND to 30,000,000 VND for 10 to under 20 invoice numbers;
- from 30,000,000 VND to 50,000,000 VND for 20 to under 50 invoice numbers;
- from 60,000,000 VND to 80,000,000 VND for 50 or more invoice numbers.
In addition to the fine, violators are required to issue invoices as prescribed (Decree 125/2020/NĐ-CP, Article 24 Section 6, as amended by Decree 310/2025/NĐ-CP, Article 1 Section 14 Point c). These fine levels apply to organizations; for business households, the fine levels applicable to individuals are used (Decree 125/2020/NĐ-CP, Article 7 Section 4 Point a). Please consult with your accountant to determine whether your case requires invoice issuance and which fine level applies to you.
Beyond tax authority risks, sellers also face risks from the e-commerce platform itself. In many cases, a seller account can be locked or restricted if found to be in violation of tax obligations.
What is the procedure if an invoice is issued incorrectly?
From 01/07/2026, incorrectly issued electronic invoices are handled depending on the type of error (Circular 91/2026/TT-BTC, Article 10 Section 1; Circular 91/2026/TT-BTC, Article 25 Section 1):
- Wrong name, address, amount in words or other content, but not wrong tax code, amount written on invoice, tax rate, tax amount or goods: notify the buyer about the incorrectly issued invoice, no need to reissue the invoice, and notify the tax authority according to Form No. 04/SS-HĐĐT (Circular 91/2026/TT-BTC, Article 10 clause 1 point a). If you send invoice data according to a summary table, or the incorrect invoice is an invoice from a cash register or an invoice for selling assets that must register ownership rights, usage rights (see final note), please consult your accountant.
- Wrong tax code, goods name or goods not meeting specifications, quality, amount written on invoice, tax rate, tax amount or other mandatory content (except invoices from cash registers and invoices for selling assets that must register ownership rights, usage rights: see final note): the seller can choose to issue an adjustment invoice or a replacement invoice. Before doing so: if the buyer is an organization, business household or individual business operator, both parties must draw up a written agreement clearly stating the incorrect content; if the buyer is an individual, the seller must notify the buyer or post a notification on the seller's website (if available). Some cases do not require a written agreement, for example selling goods on e-commerce platforms (Circular 91/2026/TT-BTC, Article 10 clause 1 point b). Regarding which period to declare taxes: please consult your accountant.
- An incorrect invoice is an electronic invoice from a cash register, or an invoice for selling assets subject to registration of ownership rights, usage rights: the seller issues a replacement invoice for the incorrectly issued invoice, except for cases specified in point c.2 clause 5 (registered assets already registered in the buyer's name that the buyer returns: if the buyer is an electronic invoice user, the buyer issues a return invoice to the seller; please consult your accountant) (Circular 91/2026/TT-BTC, Article 10 clause 1 point c, clause 5 point c.2).
- Invoices issued before 01/07/2026 according to Decree 123/2020/NĐ-CP, Decree 70/2025/NĐ-CP and Circular 32/2025/TT-BTC that are incorrect: please consult your accountant (Circular 91/2026/TT-BTC, Article 24 clause 2).
Read more: Summary of replacement invoices and adjustment invoices
Practical solutions for online sellers
In the context of increasingly transparent sales data, the safest approach is not to "avoid invoices", but to standardize processes from the beginning.
Online business households should:
- Use a management system capable of automatically issuing electronic invoices when the order is completed
- Synchronize data orders – inventory – revenue – invoices to avoid discrepancies
- Have a ready process for handling exchanges, refunds, invoice adjustments
In actual operations, many business households are choosing integrated management platforms such as GTG CRM, which allows:
- Automatically issue electronic invoices through MISA, S-Invoice
- Automatically issue replacement invoices when exchanges occur
- Integrate and synchronize products from e-commerce platforms
- Manage products, warehouse, inventory, suppliers, orders, shipping, invoices and accounting data on the same system
This approach helps reduce the risk of manual errors and meets the requirements for inspection and reconciliation when needed.
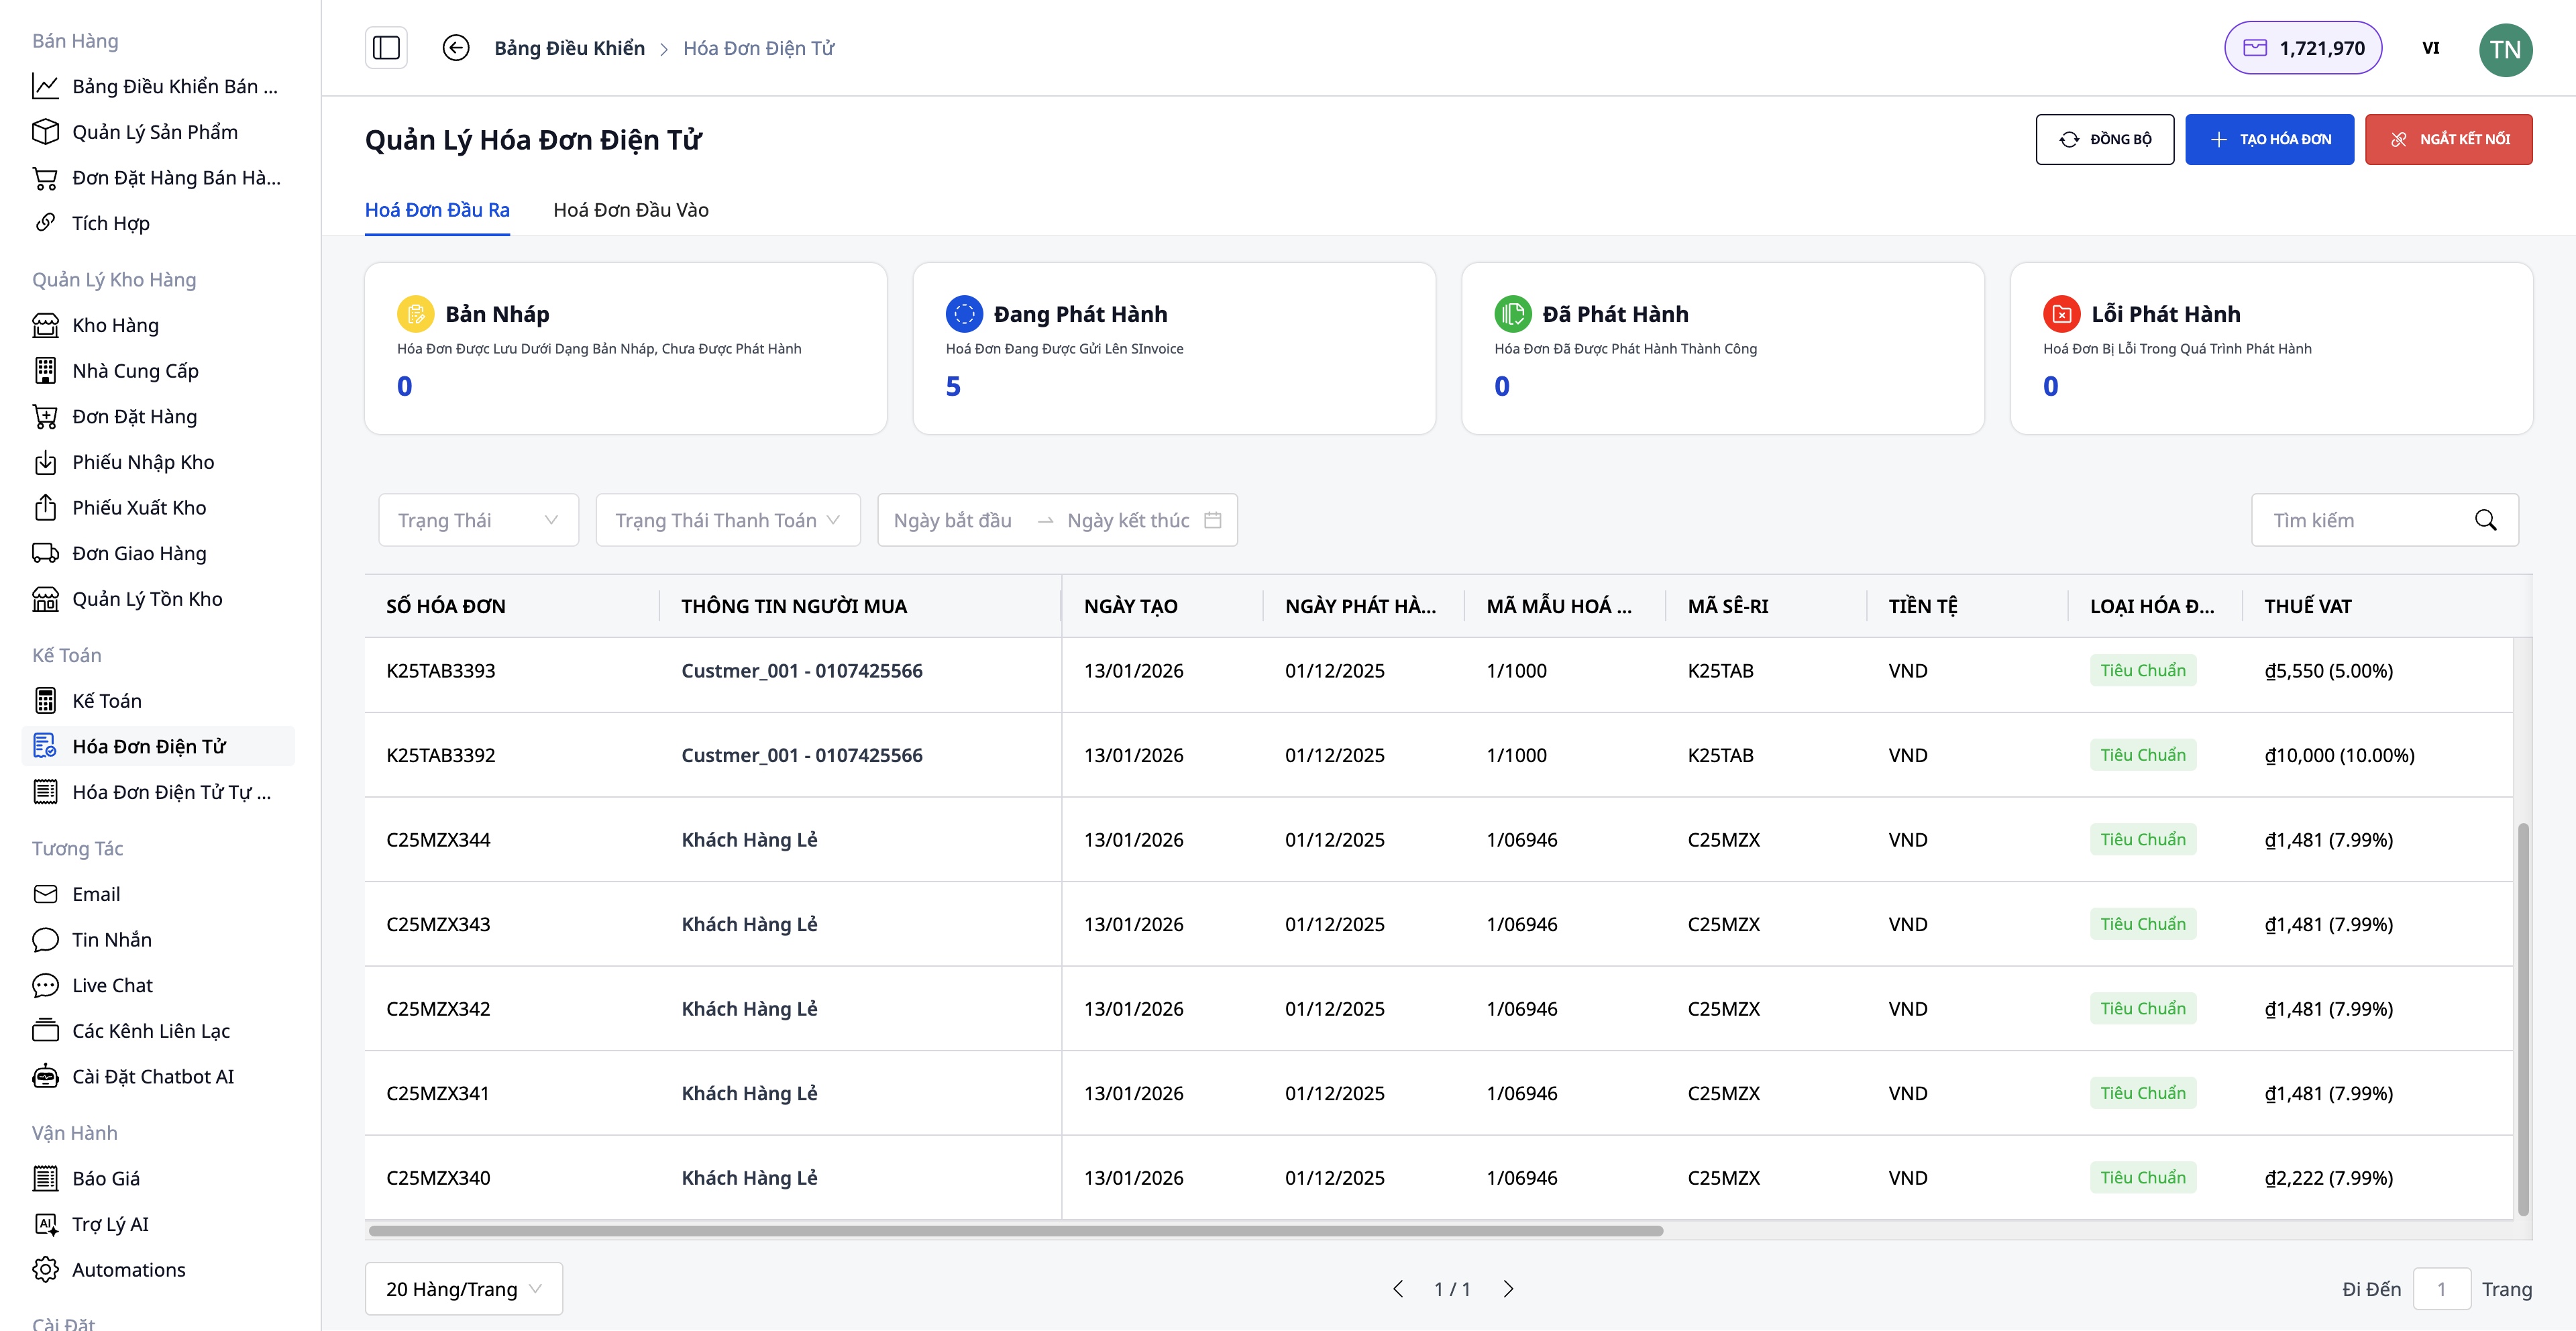
GTG CRM automatically issues electronic invoices and synchronizes products from e-commerce platforms
Conclusion
Selling online without issuing invoices is no longer a "small matter" in the current period.
Sellers need to understand clearly:
- The obligation to issue electronic invoices depends on your situation (see the beginning of this article); if you are required to issue but do not, you may be fined based on the number of invoices not issued. Ask your accountant to see if your situation requires issuing invoices
- Standardizing processes from the start is the only way to sustainable business
Electronic invoices, when required to be used, are not just an obligation, but also a tool to protect sellers against potential legal risks in the future.
Turn what you just read into real results — apply now with GTG CRM, free.
Apply now

